There is no single price for removal insurance in the UK, because the cost depends on what you own, how far it travels and who is doing the move. For many people the real question is not “how much?” but “am I already covered?”. If you book an insured professional removal company, cover for your goods in transit is part of the service, and your home contents policy may add a second layer. This guide shows what drives the price, what your existing policy probably says, and how to sort it all out before moving day. It is written for people moving house, offices, pianos and valuable furniture.
Moving is stressful enough. Insurance should be the calm part of the plan, so let’s make it that.
TL;DR
- Removal insurance (also called moving insurance) covers your belongings against loss or damage while they are packed, loaded and carried to your new place.
- The price depends mainly on the value of your goods, the breadth of cover, the excess you choose, and the distance and difficulty of the move. Antiques and designer pieces push it up.
- Many home contents policies already cover a move, but often with conditions: a professional removal company, professional packing of fragile items and value limits.
- Pianos, art, jewellery and other high-value items usually need to be declared separately, whichever policy you use.
- Read your policy wording and ask your mover about goods in transit and public liability cover before you book.
Table of Contents
- What removal insurance actually is
- How much does removal insurance cost in the UK?
- Are you already covered by your home insurance?
- Home insurance vs the mover’s insurance
- Pianos, fine art and other valuable items
- Office and business moves
- Your pre-move cover checklist
- Why an insured, full-service move makes this easier
- Ready to book an insured move?
- FAQ
- Sources
What removal insurance actually is, part of removal insurance cost UK
Removal insurance protects your furniture, family heirlooms and furnishings against loss or damage while you move home. Sainsbury’s Bank describes it as cover from the moment items are packed and loaded until they have been taken from one location to another.
You will see several names for the same idea: moving insurance, mover’s insurance, moving house insurance and goods in transit cover. They overlap, but there are three distinct things worth separating:
- Your own contents or removals cover. This protects your belongings, and you hold the policy.
- The removal company’s goods in transit (GIT) insurance. This is the company’s cover for the goods it carries on behalf of customers.
- The removal company’s public liability insurance. This covers injury to people or damage to property, such as a scratched hallway or a damaged neighbour’s gate, caused by the team.
When a company says a move is “insured”, it is usually talking about the second and third. If you want a deeper explainer, we have written about what moving insurance is and whether you need it and a full moving insurance guide.
How much does removal insurance cost in the UK? Part of removal insurance cost UK
Here is the honest answer: it varies from a few pounds added to an existing policy to a bespoke quote for a high-value load, and no official source publishes a standard UK price. Rather than quoting a number that may not match your move, it is more useful to know what moves the price. These are the usual factors:
| What affects the price | Effect on cost |
|---|---|
| Value of your goods | Higher total value means a higher premium. Antiques and designer pieces cost more to cover. |
| Breadth of cover | Adding accidental damage or extra items raises the price. |
| Excess | A higher excess you agree to pay on a claim usually lowers the premium. |
| Distance and difficulty | Long moves, narrow stairs or awkward access mean more risk. |
| Timing | Booking early can sometimes get a better price. |
These factors are set out by the insurance comparison site QuoteRadar. The practical takeaway: work out the replacement value of what you are moving before you ask anyone for a price. Walk through each room and add up what it would cost to buy everything again. Most people are surprised by the total.
A worked example
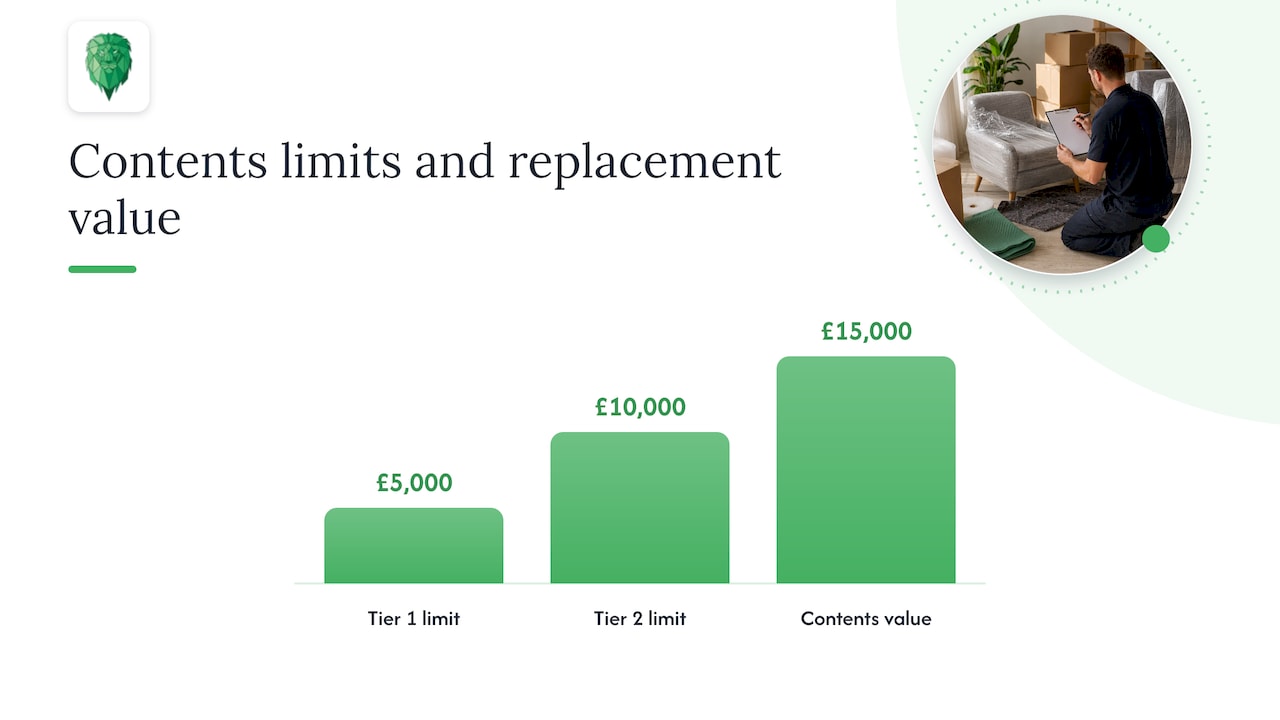
Imagine you move a two-bedroom flat with contents you would value at £15,000 to replace. Your home contents policy has a limit for contents away from the home. If that limit is lower than £15,000, part of your load is effectively uninsured in transit. In a July 2025 product comparison guide, one UK home insurance provider’s two tiers show limits of £5,000 and £10,000 for contents away from the home, with professional removal cover of up to 14 days in both. Those figures belong to that one product, not to every policy, but they show why the limit matters. Check yours.
Are you already covered by your home insurance? Part of removal insurance cost UK
Quite possibly, yes. The Homeowners Association says you don’t necessarily need separate removals insurance, because many home contents policies cover you during a move. Look in your policy for phrases like “contents cover when you’re moving home”, “goods in transit cover” or “removals cover”.
The conditions are where people get caught out. Typical ones include:
- A professional removal company. Uswitch notes that many policies cover a move only if you use a professional removal company. Ask your insurer in writing whether the type of move you have planned qualifies.
- Professional packing of fragile items. Sainsbury’s Bank, for example, excludes china, glass and fragile items unless professionally packed.
- Value limits. Cover for items away from the home, and for single valuable items, is capped.
- Undeclared high-value items. Lemonade UK lists undeclared high-value items, accidental damage not added as an extra, and poorly packed belongings among common exclusions.
- Time limits. Cover for a move often lasts only for a set period, and the same Sainsbury’s Bank page excludes temporary storage by the mover for more than 72 hours.
Also check what is left out altogether. The same insurer’s removals cover excludes valuables or money, bikes, and documents and data, and asks you to update your property details after the move.
Contents insurance vs removals insurance in one line, part of removal insurance cost UK
Contents insurance is your year-round policy for what is inside your home, and it may stretch to cover a move. Removals insurance is cover specifically for the journey, which can be included in a contents policy, bought as an add-on, or provided by the mover for the goods it carries. They are not rivals: the strongest set-up is usually your own policy plus an insured mover, so each covers a different part of the risk.
Home insurance vs the mover’s insurance, part of removal insurance cost UK
This is the part most guides skip, and it is the one that saves arguments later.
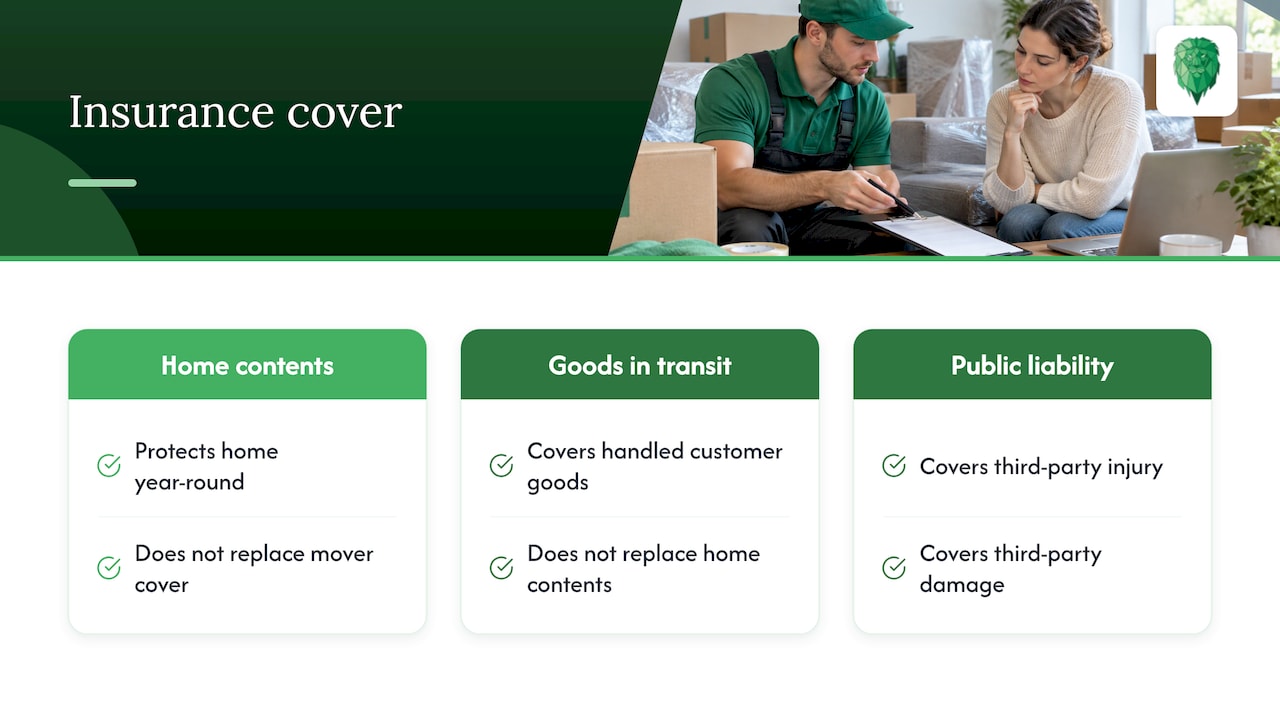
A removal company’s goods in transit insurance is there to cover the customer goods it handles. Its public liability insurance covers third-party injury and damage. Neither replaces the contents policy that protects your home year-round, and your contents policy does not replace a mover’s own cover. Having both avoids gaps.
If you want the business-side view, our guides on goods in transit insurance in the UK, GIT versus liability cover and a public liability checklist before you book go into the detail.
One point of reassurance on the rules. The Financial Conduct Authority’s PS25/21 policy statement, published in December 2025, simplified some insurance definitions. It lists goods in transit among “specialist risks contracts”, and confirms the consumer protection rules continue to apply to retail consumers who are policyholders. In plain terms: if you buy your own cover as an individual, those consumer protections still apply to you.
Pianos, fine art and other valuable items, part of removal insurance cost UK
Standard cover is built for ordinary household goods. Things worth more than the usual per-item limit need special attention:
- Pianos. Some policies cover musical instruments, including pianos, only while they are in the home, unless the instrument is endorsed on your policy schedule. One insurer’s policy wording from November 2024 also requires pianos to be insured at current market value or an agreed replacement value. So a piano needs to be named, valued and confirmed as covered in transit. Our piano removal service is built for exactly this kind of specialist item.
- Jewellery, watches and art. These are often capped per item and may need declared-value cover. Typical home policy limits for a single valuable article are modest compared with the price of fine art.
- Antiques and designer furniture. They push the price up, as the table above shows, so give your insurer a valuation or receipt.
The rule is simple: declare anything high-value when you ask for a quote, and get the confirmation in writing.
Office and business moves, part of removal insurance cost UK
If you are moving a small or medium-sized business, your office contents, IT kit and stock may be covered by a business policy rather than a home one. Check whether it includes cover while items are in transit, and for how long. We have separate guides on office move insurance in the UK and commercial move insurance questions. Servers and communications equipment deserve a line of their own on your inventory.
One tax detail for businesses moving abroad: HMRC’s Notice IPT1 says the Insurance Premium Tax exemption for goods in international transit applies only where the insured acts in the course of a business, and does not extend to private removals. For a domestic UK move this does not come into play.
Your pre-move cover checklist, part of removal insurance cost UK
The Association of International Movers advises that before booking you should ask about goods in transit and public liability insurance, read the terms carefully, and check whether high-value or fragile items must be declared separately. Here is a simple routine built on that:
- Read your contents policy. Search for “moving home”, “goods in transit” and “removals”. Note the limits, the time period and the packing conditions.
- Phone your insurer. Describe the move: date, distance, who is moving you, and any storage stop. Ask for the answer in writing.
- Make an inventory. List each room, with photos and receipts for the expensive items.
- Declare the valuables. Pianos, art, jewellery and antiques go on your list and on the quote request.
- Confirm the mover’s insurance. Ask about goods in transit and public liability cover before you book.
- Decide on packing. Fragile items packed professionally are more likely to be covered, so check your policy’s packing conditions.
- Update your details. Tell your insurer your new address and property details after the move.
If something is damaged
Photograph the item and the packaging, note it on the delivery paperwork at the time, and report it to the insurer or mover quickly. Keep your inventory and receipts handy: they make a claim far simpler.
Why an insured, full-service move makes this easier, part of removal insurance cost UK
The fewer hands your belongings pass through, the easier cover is to understand. With one company packing, loading, transporting, unpacking and, if needed, storing, you have one point of contact and one set of terms to read. We offer house removals with packing, unpacking and storage, and we can also assemble and disassemble furniture. Our temporary storage guide is worth a look if your move has a gap between homes, because storage time is one of the things policies limit.
Our view: insurance is part of the move, not an afterthought
We have been moving people and businesses around the UK for over 15 years, and one thing is constant: the people who feel calmest on moving day are the ones who sorted cover early. They know their contents limits, they have listed the valuable pieces, and they know their goods are travelling with an insured mover.
That is why we offer insured transport and specialist handling for large, fragile and valuable items such as pianos. A full-service job, where we can pack, load, transport and unpack, also means fewer unknowns about who is responsible at each stage.
Our advice is to treat the insurance conversation like measuring a doorway: boring, quick and much better done before the sofa is stuck in it.
Claudiu
Ready to book an insured move?
Tell us what you are moving, where from and where to, and we will give you an instant online quote for the job. Whether it is a flat, a full house, a piano or an office, you can add packing, storage or furniture assembly in the same booking.
Start with our house removals page, or see how man and van and furniture removals can fit a smaller move.
FAQ
Is removal insurance compulsory in the UK?
No law requires you to buy it for a private move. It is a sensible protection, though, and your mortgage lender or landlord may have their own expectations about the property. Check what your contents policy already includes before paying for more.
Does home insurance cover my belongings in a removal van?
Often, but with conditions. Many policies cover a move only when a professional removal company is used, and they may require professional packing of fragile items and set value limits. Read the wording or ask your insurer to confirm it for your specific move.
Do I need separate insurance for a piano?
Check first. Some policies cover pianos only while in the home unless they are specifically endorsed, and they may require the piano to be insured at market or agreed value. Tell your insurer and your mover about the piano when you request quotes.
What does “insured removals” mean?
It means the removal company carries insurance, usually goods in transit cover for the items it moves and public liability cover for damage or injury. Ask what the limits are and whether high-value or fragile items must be declared.
Can I claim for items I packed myself?
It depends on the policy. Some exclude fragile items such as china and glass unless professionally packed, so read the packing condition before you start wrapping.
Sources
- Household Removals Cover, Sainsbury’s Bank
- Furniture Removal Insurance, QuoteRadar
- Gold and Platinum Home Insurance Policy Limits Comparison, July 2025
- Insurance When Moving House, Homeowners Association
- Your guide to insurance when moving home, Uswitch
- Does Contents Insurance Cover Moving House?, Lemonade UK
- PS25/21: Simplifying the insurance rules, FCA
- SCOR Policy Wording, November 2024, Stanhope
- Notice IPT1: Insurance Premium Tax, GOV.UK
- 7 Questions to Ask Before Booking a Removal Company, AIM